

Dave: Credit, Cash & Money App

- 232.92K Reviews
- 4.7
- Downloads
- 10,000,000+
Our take on Dave: Credit, Cash & Money App from Appgk
I look at Dave as a short-term money-management app rather than a complete replacement for a bank account. It belongs in the finance category, is free to install, and is made by Dave Operating LLC. In everyday use, its appeal is easy to understand: when a paycheck is still a few days away and an unexpected expense appears, the app is designed to help eligible users access cash without a credit check or interest. That can be useful, but it also requires careful household planning because quick access to money is not the same thing as having more money.
I found the app most interesting in situations where timing is the real problem. A household may have enough income for the month overall, yet still struggle when a utility bill, prescription, school expense, or necessary repair arrives before payday. Dave focuses on that gap. My main advice is to treat it as a temporary bridge, not as part of the regular monthly budget. If you already need early access every pay cycle, the app may be highlighting a deeper cash-flow problem that a written budget, bill negotiation, or a different banking arrangement would address more effectively.
How Dave fits into a shared household
A realistic shared-device situation
Imagine two adults sharing a phone or occasionally handing the same tablet around at home. One person notices that the household balance is tight and opens Dave to check whether an advance could help cover groceries until payday. That moment sounds simple, but finance apps should not be treated like entertainment apps that everyone can open casually. The person using the app should be the account holder, and other household members should avoid browsing through personal financial information just because the device is shared.
This is where Dave can be useful and where it can create confusion. The app gives one person a way to manage their own short-term cash position, but it does not turn a shared household into a single financial account. I would use it as a personal financial tool while discussing the resulting repayment or account activity with anyone who shares the budget. That keeps the decision visible without handing over private login details or allowing several people to make separate choices from one account.
Best Parts of Dave: Credit, Cash & Money App
Things to Keep in Mind About Dave: Credit, Cash & Money App
A practical routine is to decide in advance who checks the app, who records any money received, and how the household will handle the next payday. That small conversation matters more than simply installing the application. If one person requests money without telling the other, the household may mistake temporary relief for extra spending room. The best use is coordinated: identify the exact bill, agree on the repayment plan, and avoid using the advance for optional purchases.
Keep personal access separate from household discussion
Dave is not something I would leave open on a shared device. A finance app can expose sensitive details through its screens, notifications, or account history, so I would sign out or use the device's normal security protections after checking it. I would also avoid saving access details where another person can easily see them. These are basic habits, but they become especially important when partners, roommates, older children, or visiting relatives use the same phone.
News and Features Related to Dave: Credit, Cash & Money App

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
Household coordination does not require sharing every private detail. A couple can agree on the amount needed, the purpose, and the expected repayment timing without passing around account credentials. Roommates may need to know only that one person is handling a personal shortfall and that rent or utilities remain covered. That distinction helps prevent Dave from becoming an informal joint wallet when it is actually an individual finance app.
For a shared household, I would write the planned use in a simple note: what expense the money covers, when the regular income arrives, and which account needs to remain funded. This is one of the most useful habits because the app can make access feel immediate, while the household consequences arrive later. A written reminder turns a quick tap into a deliberate decision.
Don't want to read the full review?
Setup should happen with the right person present
When setting up Dave, I would use the account holder's own phone, email, and financial information rather than trying to create a household profile from someone else's details. The person whose finances are being evaluated should read each screen and make the decisions. A partner can sit nearby to help understand the budget, but the account should remain under the correct person's control.
This boundary is important on a family device. A parent might help an adult child understand the app, but that does not mean the parent should enter information on the child's behalf or keep access afterward. Likewise, a roommate should not use another roommate's account simply because the latter has the device or bank connection available. Keeping identities separate reduces the chance of mistaken activity and makes it easier to know who is responsible for the transaction.
Screenshots
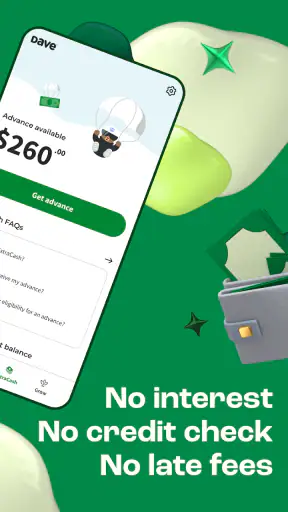
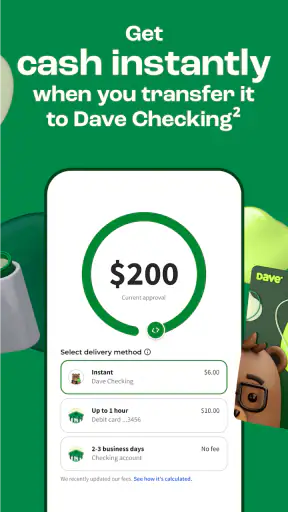
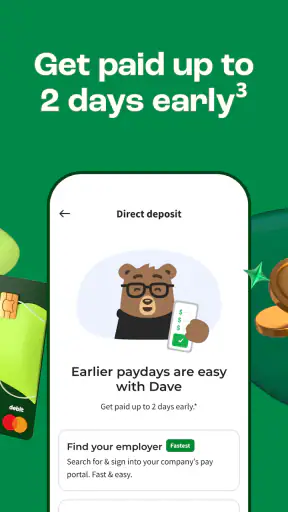
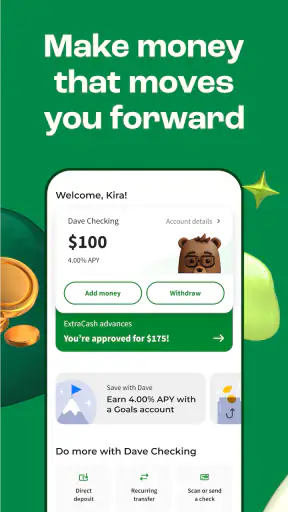
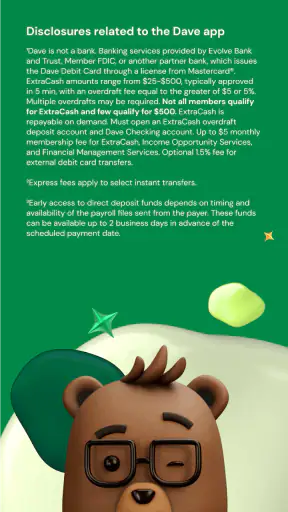
I would also slow down at any point involving connected financial accounts, repayment arrangements, or optional services shown during setup. The most useful question is not just “Can I get money now?” but “What will this do to the next pay cycle?” Read the amount, timing, and any on-screen terms before confirming. A free app can still involve financial consequences, and free installation should never be confused with cost-free borrowing in every possible situation.
What the app is good at—and what it cannot solve
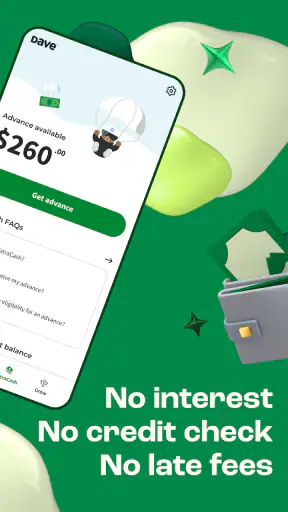
The core attraction is speed and accessibility. Dave's store summary presents access to as much as 500 dollars, with no credit check and no interest, which makes it different from a conventional credit card or many personal-loan applications. That may help someone who has income but a thin credit history or does not want a hard borrowing process for a small, urgent need.
Still, I would not describe the app as a general emergency fund. An advance has to fit into the user's future cash flow. If the next paycheck is already committed to rent, debt, food, and transportation, receiving money early can simply move the shortage forward. In that situation, asking a provider for a payment extension, using an existing savings cushion, or speaking with a trusted person may be safer than repeatedly relying on early access.
Dave also should not be confused with a traditional budgeting application whose main purpose is long-term planning. Budgeting tools can help users categorize spending, set targets, and build savings habits. Dave's most recognizable value is closer to short-term liquidity. I would use a budgeting method alongside it, not expect the app alone to tell me whether a request fits the whole month's obligations.
Coordination before and after receiving money
A good household workflow has three checkpoints. Before using the app, identify the exact expense and confirm that it is necessary. Immediately afterward, record the amount in the household budget rather than mentally treating it as ordinary income. Before payday, check that the account expected to cover the repayment or related movement still contains enough money after essential bills are considered.
This process is particularly helpful when income arrives into one account but expenses are split between several people. For example, one partner may request help for a car-related expense while the other pays groceries. Without a shared note, both people may spend as if the original balance were still available. Dave can support the first person's timing problem, but only communication prevents the second person's budget from being affected by surprise.
I would also avoid making several small requests simply because each one feels manageable. Fragmented decisions are harder to track than one clearly defined need. If the household cannot explain what each request is for and how the next income will absorb it, that is a warning to pause. The app should make a specific short-term problem easier to handle, not make recurring shortfalls harder to see.
Age, trust, and financial responsibility
The content rating is Everyone, but that label should not be interpreted as a signal that every child can independently use the service. Finance apps involve personal information and real financial decisions. In my view, an adult should manage the account and any borrowing decision. Younger household members may see the app on a shared device, yet they should not be invited to experiment with it or treat the available amount as spending money.
For teenagers, the more valuable lesson is how timing affects a budget. An adult can explain why money arriving early still has to be accounted for later, without giving the teenager control of the account. For older relatives who are less comfortable with mobile finance, assistance should focus on reading screens and understanding choices rather than taking over the account. Trust works best when the account owner remains the person making the final decision.
I would be especially cautious if several adults use the same device but have different banking arrangements. A familiar name or saved screen can create a false sense that the account belongs to everyone. Before confirming anything, check whose profile is active and whose financial information is being used. That simple pause is a practical safeguard in homes where devices and chargers move from person to person.
Privacy and boundaries in everyday use
Dave's usefulness depends on personal financial context, so privacy is part of responsible use. I would avoid discussing account details in a crowded room, displaying the balance on a television-connected device, or allowing someone to photograph a confirmation screen. These precautions are not unique to Dave, but they matter more when the app is used as part of a household conversation about shared bills.
At the same time, privacy should not become secrecy when the money affects joint obligations. If an advance changes the amount available for rent, food, or transportation, the relevant household member needs to know. The right balance is to share the budget impact, not every private account detail. That approach protects the user while keeping the household plan realistic.
Questions I would answer before installing it
Would I use Dave for a one-off timing problem? Potentially, yes, if the expense were necessary, the next income were dependable, and the household budget clearly showed how the shortfall would be absorbed. Would I use it for recurring groceries or regular bills? I would be much more hesitant. Repeated advances can conceal that monthly expenses are higher than income, and the convenience may make that pattern feel normal.
Is it suitable for someone worried about a credit check? The store summary specifically presents access without a credit check and without interest, which is a meaningful distinction from many credit products. Even so, I would still read the current in-app terms carefully and consider the effect on the next pay cycle. “No interest” does not mean a user can ignore timing, account balances, or any other conditions shown during use.
Can it replace a bank account? I would not approach it that way. Dave is better understood as a finance app for managing a short-term cash need. Someone looking for full household banking, joint ownership, long-term savings, or a comprehensive bill system should compare it with a bank account and a dedicated budgeting tool. The right choice depends on whether the main problem is access to money now or control over money across the entire month.
Who should skip it? I would skip it if the household has no reliable plan for the next income, if the request is for discretionary spending, or if using the app would hide an ongoing deficit from a partner. I would also avoid putting it on a shared device without clear account boundaries. A tool that helps one person in an emergency can become a source of tension when several people assume they can use it or when nobody records the future impact.
What the app's scale tells me
Dave has a 4.7 average from around 620 thousand ratings, and it has passed 10 million installs. That level of adoption suggests the short-term cash problem it addresses is common, and many users find the experience useful enough to rate positively. I see those figures as evidence of broad interest, not as a guarantee that the service will fit every household's finances.
The app is free and rated for Everyone, which lowers the barrier to trying it. Its release history goes back to April 24, 2017, so it is not a brand-new experiment in the finance space. The current version is 4.9.1 and requires operating system 9 or later. Before installing on an older phone, I would check the device software and make sure the account holder has enough storage and a secure screen lock, especially if the phone is shared.
Those details also explain why I would not judge Dave solely by the promise of immediate cash. A mature, widely used app can still be the wrong tool for a particular financial situation. The important test is whether the household can use it transparently, protect the account, and handle the next stage without sacrificing essential expenses.
My household verdict
After considering the shared-device and shared-budget angle, I see Dave as a focused option for a narrow but real problem: getting through a short gap before regular income arrives. I like that the app's central proposition does not depend on a traditional credit check or interest, and I can see why that would matter to someone facing an urgent expense. The free entry point and straightforward purpose also make it easy to investigate.
My reservation is behavioral rather than cosmetic. The easier it feels to access money, the easier it is to stop noticing the underlying gap. In a household, that risk grows when one person uses the app privately while another person plans around the original balance. I would recommend it only with a specific purpose, a clear repayment plan, and an agreement about what information needs to be shared.
For a one-time timing issue, Dave may be more practical than a credit card application or a conventional personal loan, particularly for someone who wants to avoid a credit check and interest. For ongoing financial pressure, I would choose a proper budget review, an emergency savings plan, or a conversation with creditors before making early access part of the routine. My bottom line is simple: use Dave as a carefully tracked bridge, never as permission to spend beyond the household's real income.
Dave: Credit, Cash & Money App FAQ
What is Dave: Credit, Cash & Money App, and how does it work?
Dave is a personal finance app designed to help users manage everyday money needs through features such as spending accounts, budgeting tools, automatic savings options, and access to eligible cash advances. After creating an account and connecting a qualifying bank account, the app reviews available information to determine which services may be offered. Features, limits, fees, and eligibility can vary by user.
Can Dave provide an advance before my next payday?
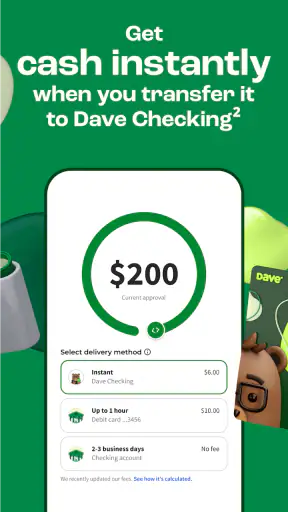
Eligible users may be able to request a small cash advance through Dave to help cover an unexpected expense before payday. Approval is not guaranteed, and the available amount depends on factors such as account activity, income patterns, repayment history, and other eligibility requirements. Delivery speed, optional express-transfer charges, and repayment terms should be reviewed carefully before confirming a request.
Does Dave charge fees or require a subscription?
Dave may offer certain services through a membership or recurring fee structure, while other features can involve optional charges depending on how they are used. For example, faster delivery of an advance may cost more than a standard transfer. Pricing and terms can change, so users should check the current fee disclosures inside the app before signing up, requesting money, or allowing a recurring payment.
Is Dave a bank, and is my money protected?
Dave is a financial technology company rather than a traditional bank, and some banking services may be provided through partner institutions. Depending on the specific account and program terms, funds may receive applicable protections, but users should not assume every balance or feature has identical coverage. Read the account agreement, privacy policy, and disclosures to understand how funds are held and protected.
What information does Dave require, and is the app safe to use?
To provide financial services, Dave may request personal details, identity verification information, and permission to connect a supported bank account. The app uses security measures intended to protect account information, but no online service is completely risk-free. Download it only from an official app store, use a strong unique password, review connected accounts and permissions, and contact official support if you notice suspicious activity.











